Short answer
Solar panel insurance is a policy that protects a solar energy system against external damage such as hail, fire, storm, theft and electronic failure; it covers risks the manufacturer's warranty does not. In Antalya hail and storm stand out on the west coast and fire in summer. Always check the sum insured, deductible and exclusions in writing in the policy.
Key takeaways
- A panel warranty covers production defects; separate insurance is needed for hail, fire and theft.
- The fastest wind measured in Antalya is 43.2 m/s (MGM, 22.01.1998).
- Typical resistance in panel datasheets is 2400 Pa for wind and 5400 Pa for snow.
- In a policy, the sum insured, deductible and exclusions are as important as the premium.
- Installation contrary to the installation manual can void the manufacturer's warranty.
Solar panel insurance is the general name for policies that financially protect your solar energy system against damage such as hail, fire, theft, storm and electrical failure. It is not the same as a warranty: a warranty covers the manufacturer's production defects, while insurance covers sudden damage caused by external factors. In this article we explain, at a general-information level, which types of damage stand out for a rooftop or ground-mounted system in Antalya and what you should watch for in a policy.
The difference between insurance and a warranty
The two concepts are often confused. The panel manufacturer's product warranty covers material and workmanship defects; the performance warranty commits to the panel's power declining along a specific linear curve. For example, the datasheet of the TommaTech 605 W monofacial TOPCon panel includes a 15-year product warranty and a 30-year performance warranty. These warranties generally do not cover external events such as hail, fire or theft.
This is where insurance comes in. A panel breaking in a storm, the system being damaged in a roof fire or equipment being stolen from the site may fall outside the warranty. Coverage varies according to the policy terms. If you would like to see warranties in detail, take a look at our article on solar panel warranty terms.
Damage risks that stand out in Antalya
The need for insurance varies with the system's location. Antalya's climate is advantageous for solar, but the region also has its own particular risks.
- Hail and storm: On Antalya's west coast, around Kumluca, Finike and Demre, events in which hail, storms and tornadoes damaged greenhouses are on record; for example, in January 2019 about 1,000 decares (dönüm) of greenhouses were damaged. Because we could not find MGM (the Turkish State Meteorological Service) province-level hail frequency statistics, we cannot give a numerical hail risk.
- Wind: According to MGM records, the fastest wind measured in Antalya is 43.2 m/s (22.01.1998). Typical wind resistance in panel datasheets is 2400 Pa and snow resistance is 5400 Pa. It is important that the mounting system is designed for these loads.
- Fire: Because of summer heat and dry vegetation, forest and roof fires are an environmental risk. According to the datasheet, the panel must be mounted over a fire-resistant surface with sufficient ventilation behind it.
- Lightning and overvoltage: In stormy winter months, surge protection for the inverter and grid connection comes into question.
- Theft and vandalism: Especially on ground-mounted systems and at remote orchard houses, panels, cables and batteries can be targets.
In Antalya most rainfall occurs between November and February; the average number of rainy days in July and August is about 0.5. This shows that damage risk is distributed seasonally: storms in winter, fire and heat in summer. You can find the effect of climate on system performance in our article on Antalya's climate and panel performance.
What does solar panel insurance cover?
Policies differ from company to company; the table below offers only a general framework. Always confirm which coverage is included from the policy text and your agent.
| Coverage / risk | What it generally means | Point to check |
|---|---|---|
| Fire and lightning | Damage resulting from fire, lightning strike and explosion | Whether panels are included in a roof fire |
| Natural disasters (hail, storm) | Hail, storm and similar weather events | Whether there is a deductible or limitation for hail |
| Theft | Theft of equipment | Security measure requirements, ground-mount conditions |
| Electronic device / machinery breakdown | Sudden failure of the inverter and electronic components | Wear and tear, ageing and manufacturing defects may be excluded |
| Loss of profit / business interruption | The commercial impact of lost production | May be optional for commercial systems |
| Erection all risks insurance | Damage during installation | Contractor and employer scope on large projects |
For residential systems, additional coverage is sometimes added to the existing home insurance; for commercial and ground-mounted systems, a separate policy may be issued. Which route is suitable depends on the system's capacity, location and owner.
Points to watch in the policy
When taking out solar panel insurance, looking only at the premium amount is not enough. We recommend paying attention to these items:
- Sum insured: The system's replacement value should be used. An insufficient sum can create the risk of proportional payment in the event of damage.
- Deductible (excess): Shows how much of the damage will be yours. A separate deductible may apply for risks such as hail.
- Exclusions: Wear and tear, misuse, manufacturing defects and incorrect installation are excluded in most policies. According to the datasheet, installation contrary to the manual voids the warranty; a similar approach can come up in an insurance inspection.
- Installation documents: The project, acceptance document, photos and equipment serial numbers are critical evidence at the time of damage.
- Systems with batteries: Lithium battery capacity, placement and fire safety should be stated separately in the policy.
- Policy term and renewal: As the system ages, the sum insured needs to be updated.
We give no price here, because the premium amount, scope of coverage and deductibles vary by company and system. Comparing quotes on the same coverage and the same deductible conditions gives a fair comparison.
Insurance needs by system type
Not every system carries the same risk, so solar panel insurance is not structured the same way in every project. On a small system on a villa roof, fire, storm and inverter failure stand out the most. If a villa in Belek or Manavgat has a hybrid inverter and a lithium battery, the placement and ventilation of the battery room also become part of the policy assessment.
Ground-mounted systems, on the other hand, are more exposed in terms of theft, vandalism and natural disasters. In inland areas such as Korkuteli and Elmalı, for open-ground systems, perimeter security measures such as fencing, lighting and cameras may be among the conditions insurers ask for. On greenhouses and lightweight-structure roofs, wind load and hail are decisive.
On commercial and industrial roofs, for example at a facility in the Antalya OSB (organized industrial zone), the financial loss that would arise if production stops also comes into play. In such systems, business interruption cover is assessed separately. Whichever group your system falls into, make the policy request in writing on the basis of those risks.
Sound installation is the first condition of insurance
Even if insurance covers the damage, preventing the damage in the first place is cheaper and safer. For this reason insurance and engineering complement each other. In a properly designed system, the following measures reduce the likelihood of damage:
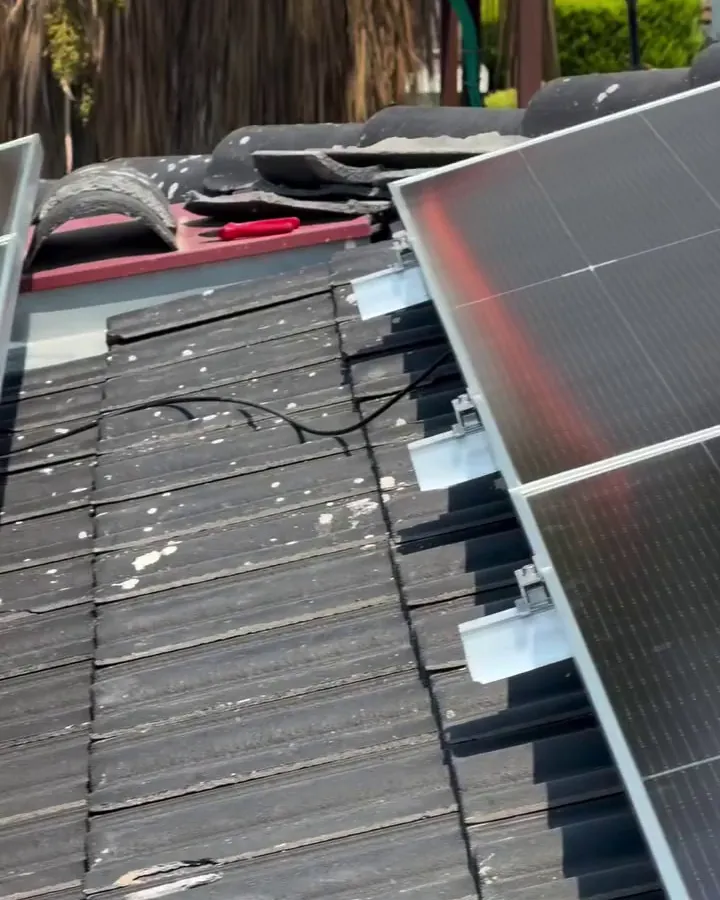
- The mounting system is chosen according to the region's wind load and the roof type; different solutions are needed for tile, sandwich panel or reinforced concrete roofs.
- Grounding, surge arresters and overvoltage protection are added to the project. You can find the details in our article on lightning and storm protection for solar plants.
- DC cable connections, connectors and panel board connections are checked regularly.
- For fire safety, ventilation behind the panel and the non-combustible surface requirement are observed; for details, see our article on fire safety for solar plants.
- Regular maintenance is carried out and records are kept.
Panels must not be installed on non-fire-resistant roofs such as plastic or PVC without a fire protection layer. This matters for both safety and warranty. Greenhouse roofs and lightweight structures also need additional protection and mounting measures.
What should you do when damage occurs?
Acting correctly after damage makes the compensation process easier. For your safety, first switch off the system and do not touch damaged equipment, because a damaged panel can still produce voltage in daylight. Then take photos of the damage, notify the insurance company or agent in writing and ask the registered installer for a technical assessment.
Keeping the documents from the installation and commissioning period is also useful in this process. Solar Nexo offers post-installation maintenance and technical support; according to the information on its website, technical support runs 24/7. The system's maintenance history creates a concrete record in establishing the cause of the damage. For planned inspections, take a look at our article on solar energy system maintenance.
Conclusion
Solar panel insurance is the second layer of security against external damage that the warranty does not cover. In Antalya, assess the risks of hail, storm, fire and theft according to your location; in the policy, look especially at the sum insured, the deductible and the exclusions. The information in this article is a general framework; for binding coverage, rely on your insurance agent's written quote. To discuss insurance needs together while designing your system, you can request a free site survey.
Frequently asked questions
Is solar panel insurance mandatory?
We could not verify a general insurance requirement for solar energy systems in official sources. However, financing, loan or commercial contract terms may require insurance. Even if it is not mandatory, taking out a policy for risks such as hail, fire and theft provides financial security. For definite information, consult your insurance agent. Even where a policy is not mandatory, because equipment value is high, most system owners prefer to balance the risk with insurance.
Does a solar panel warranty cover damage?
No. A panel warranty covers production defects and performance decline; it generally does not cover damage from external causes such as hail, fire or theft. For example, the TommaTech 605 W panel has a 15-year product and a 30-year performance warranty. A separate insurance policy is needed for external damage. In short, the warranty covers the manufacturer's defect, while insurance covers sudden damage from external causes such as hail, fire and theft.
Can hail damage panels in Antalya?
On Antalya's west coast, around Kumluca, Finike and Demre, events in which hail and storms damaged greenhouses are on record. However, because we could not verify MGM's province-level hail frequency statistics, we give no numerical risk. According to your location, make sure the hail coverage and deductible are clearly written in the policy. On ground-mounted and greenhouse roofs the risk may be more pronounced because of lightweight structures; in that case the scope of coverage should be examined more carefully.
What damage does solar panel insurance cover?
In general, coverage such as fire, lightning, storm, hail, theft and electronic device breakdown may be offered. Scope varies by company and policy; wear and tear, ageing and manufacturing defects are mostly excluded. You should check the coverage table, the sum insured and the deductibles in the policy in writing. Having the sum insured reflect the system's replacement value reduces the risk of underpayment at the time of damage.
How is the solar insurance premium calculated?
The premium is set by the insurance company based on the system's sum insured, the selected coverages, the location, the capacity and the deductible. We cannot give an amount here because it varies from company to company. Getting several quotes on the same coverage and the same deductible provides a fair comparison. When comparing premium quotes, look not only at the amount but also at the scope of coverage, the sum insured and the deductible terms.
What should be considered when insuring a system with a battery?
The battery's capacity, brand-model information and placement should be clearly stated in the policy. The fire safety and installation location of lithium batteries matter in the insurance assessment. Battery warranty differs by brand and model; for example, the product warranty on TommaTech LV batteries is 60 months. The ventilation of the installation location and fire safety measures can also directly affect the policy terms and any damage assessment.
Which documents are requested in case of damage?
Generally the policy, project and acceptance documents, equipment serial numbers, photos of the damage and a technical assessment report are requested. For this reason, keep the project and photos from the installation. After damage, switch off the system and, without touching damaged equipment, notify the insurance company in writing. Damage photos and maintenance records form important evidence in establishing the cause and speeding up the compensation process.
Sources
Want a clear calculation for your roof?
The Solar Nexo team carries out a free site survey at your address in Antalya and designs the system that suits your roof, consumption and budget.